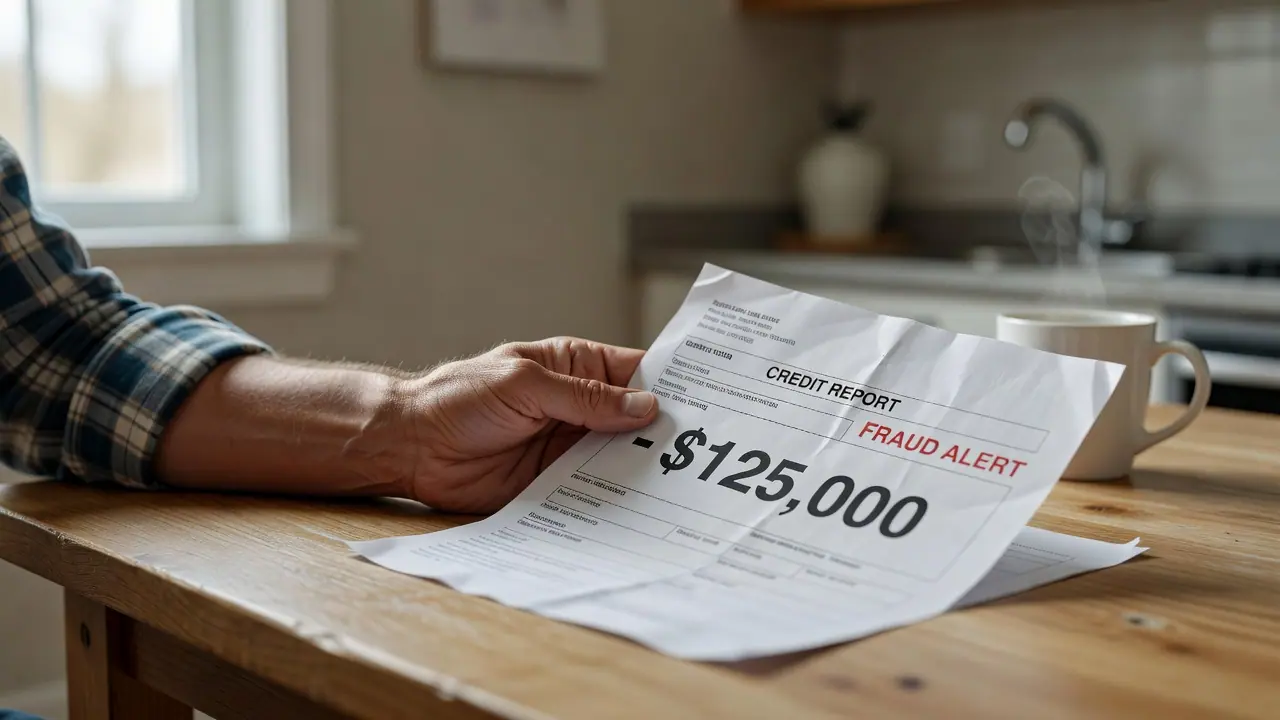
When someone's identity is used to take out a loan, the burden of untangling it often falls on the victim, so acting quickly matters. A police report, written disputes and fraud alerts with the credit bureaus are usually the strongest first steps toward getting a fraudulent debt cleared.
A North York man found himself facing more than $125,000 in debt for a pickup truck he says he never bought, after someone used his identity to buy the vehicle and finance it in his name. CP24 reported the case on November 17, 2026. It shows how quickly identity theft can turn a family's finances upside down, and why it helps to know where to find trusted legal guidance.
The man says that last month a letter arrived from his insurance company congratulating him on buying a 2026 GMC Sierra 1500 Elevation pickup truck. Surprised, he called the insurer to ask what it was about. The family then confirmed with the dealership that it had sold a truck to someone using his name, date of birth and address. According to the report, the buyer used an altered driver's licence along with his banking information and other documents. The licence carried the man's personal details but a different photo.
The loan was set at nearly $1,500 a month for seven years, which adds up to more than $125,000. Even though he did not have the truck, the man was told he had to start making monthly payments. His son is helping him with the case and asked to be identified only by his initials because he now worries about his own identity. He told CP24 the hardest part was that nobody seemed to believe them, because on paper everything made it look as if they had bought the truck. The family has also filed a fraud report with police. All they want, the son said, is to get their lives back and have the debt removed from his father's credit report.
In a statement, the dealership said it is aware of the matter and takes it seriously. It described the case as identity theft in which both the man and the dealership were defrauded. The dealership said it understands that the people behind the scheme used falsified identification while posing as the man. It said the truck was delivered to the person behind the fraud, has since been reported stolen, and police are looking for it. The dealership said it reported the fraud as soon as it was discovered and is cooperating fully with the Durham Regional Police Service. It is also working with the financial institution, which told the dealership that its own investigation is ongoing and that privacy laws prevent it from sharing details. The dealership added that fraud is at an all-time high and that organized identity and vehicle fraud is affecting consumers and dealerships across Ontario. It said it follows established identity verification procedures and continues to review and strengthen them.
The story ended well. The man has now been cleared of buying the truck, the vehicle has been declared stolen, and the debt has been forgiven. The report advises anyone whose identity is stolen to check with all of their lenders. They may need to freeze or close accounts and change passwords and PINs. They should also ask the credit reporting bureaus to put a fraud alert on their file so suspicious activity can be watched for.
Key Takeaways
A North York man was told to pay a loan of nearly $1,500 a month for seven years, more than $125,000 in total, for a 2026 GMC Sierra he says he never bought
According to the report, the buyer used an altered driver's licence with the man's details but a different photo, plus his banking information and other documents
The dealership says it reported the fraud and is cooperating with Durham Regional Police, and that the truck has been reported stolen
The man has since been cleared, the truck has been declared stolen, and the debt has been forgiven
Identity theft victims should contact their lenders, secure their accounts, and ask credit bureaus to place a fraud alert on their file
UL Lawyers Insight
For Ontario residents, this case shows that identity fraud can leave you facing a large loan you never agreed to. Your name, date of birth, address and banking details can be enough for someone to finance a vehicle, especially when combined with a forged licence. The family's experience also shows a common frustration: until the fraud is confirmed, lenders may treat the paperwork as genuine and expect you to pay.
This story was resolved without going to court. Not every case goes that smoothly. If a lender keeps demanding payment, sends the account to collections, or refuses to correct your credit file, speaking with experienced litigation lawyers can help you understand how to formally dispute the debt and protect your credit history.
The early steps matter most. A police report, written disputes with the lender, and fraud alerts with the credit bureaus create a record that supports your position. Our legal resource library offers more plain-language guidance on protecting your rights in consumer and financial disputes.
Action Checklist
What You Should Do
File a police report about the identity theftUrgent
A police report number is key evidence when you dispute fraudulent loans with lenders and credit bureaus
Contact the lender and dispute the debt in writingUrgent
Explain that you did not apply for or authorize the loan, and keep copies of everything you send
Request a fraud alert from Equifax and TransUnionUrgent
A fraud alert tells creditors to verify your identity before approving new credit in your name
Check with all of your lenders and freeze or close compromised accountsUrgent
Stolen banking information can be used again, so secure every account that may be affected
Change your passwords and PINsUrgent
Update banking, email and other account logins to cut off further access
Get a copy of your credit report and review it
Look for other unfamiliar accounts or inquiries and dispute any errors under the Consumer Reporting Act
Keep a log of every call, letter and email
Note dates, names and what was said to build a clear record if the dispute escalates
Speak with a lawyer if the lender will not release you from the debt
Legal advice can help you understand your options and the two-year Limitations Act deadline
Your Rights and Options
If a loan appears in your name that you never signed or authorized, you have the right to dispute it with the lender and with the credit bureaus. Ontario's Consumer Reporting Act gives you the right to see what is in your credit file and to challenge information that is inaccurate. That includes a fraudulent vehicle loan like the one in this story. A police report, like the one this family filed, is often key evidence when you dispute the debt.
If a lender refuses to release you from the debt, or the false entry damages your credit and causes you financial loss, you may have legal options. Under Ontario's Limitations Act, 2002, you generally have two years from when you discovered the problem to start a civil claim, so it is important not to wait. If you are unsure where you stand, you can request a consultation to review your situation.
Common Questions Answered
How UL Lawyers Can Help
Finding out that someone has taken on debt in your name is overwhelming. It can be especially hard when it feels like no one believes you. You should not have to fight a lender or a credit bureau on your own. At UL Lawyers, we can review your documents and help you organize your evidence. We can also communicate with lenders on your behalf and explain your options in plain language, including what to do if a dispute does not resolve on its own. We offer a free consultation so you can talk through your situation with no pressure and decide what is right for you.
Dealing with a loan or account you never opened? Talk to our team about how to dispute it and protect your credit.
About this article:
Summary prepared with AI assistance from the linked source's reporting. Edited by UL Lawyers for Ontario context.
Accompanying images are AI-generated illustrations, not photographs of actual events or persons.
Important Legal Disclaimer
This page provides general information about an identity theft case reported in Ontario and is not legal advice. Every identity fraud or debt dispute depends on its own facts, and laws and deadlines can change. If a loan or account has been opened in your name without your consent, please consult a lawyer about your specific situation.
Source: CP24
Named in this article? Request content removal